Web3 is a vision for an internet in which people can use blockchain networks to hold digital assets, access applications and, in some cases, help govern the services they use. Unlike the conventional platform model, where an app usually controls your account and database records, Web3 can let you interact through a crypto wallet and independently verify certain transactions.
Web3 crypto coins are the cryptocurrencies and tokens that support this ecosystem. Some pay blockchain transaction fees; others are used for storage, data services, governance or incentives. Not every cryptocurrency is a Web3 infrastructure token, and owning one does not mean you own a Web3 company.
Web3 (also written Web 3.0) commonly refers to blockchain-based services designed around decentralisation, programmable transactions and digital ownership. Rather than relying exclusively on a single company to maintain every record, a Web3 application may use a distributed network and smart contracts to manage part of its activity.
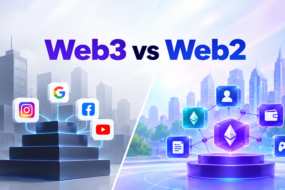
A useful shorthand is Web1 = read, Web2 = read and write, Web3 = read, write and own. These are broad labels, not official internet versions with fixed starting dates. Web2 is still widely used, and many services described as Web3 combine centralised and decentralised technology.
The differences in ownership, identity and data control become clearer in a side-by-side Web2 vs Web3 comparison, which explains both the potential advantages and the limitations of decentralised applications.
A typical Web3 experience involves four components:
For example, instead of depositing an asset into a game operator’s database and trusting it to recognise your balance, a blockchain game may represent a transferable item as a token in your wallet. This does not guarantee that the game will remain available or that the item will retain value.
Imagine opening a decentralised exchange through a browser. You connect a compatible wallet, which identifies your blockchain address without giving the website your secret recovery phrase. When you request a token swap, the application prepares a transaction describing which assets you intend to send, the expected output, any network fee and the permissions required. You should check every detail before signing. The wallet signature authorises the request; it is not a conventional password login.
The signed transaction is broadcast to a blockchain network, where validators check that it follows the rules. If confirmed, the blockchain updates the balances or contract state. A block explorer can show the transaction identifier, network, fee and confirmation status. However, this transparency does not mean the price was fair or the application was safe. Malicious contracts and incorrect addresses can still create irreversible losses.
Web3 is not a single application. It is a collection of technologies, and each layer has a different job. A layer-1 blockchain, such as Ethereum or Solana, provides the network on which transactions are recorded. Some ecosystems also use layer-2 systems to process transactions more efficiently while relying on another blockchain for parts of their security. Smart contracts implement application logic, including transfers, exchanges and governance rules.
Other networks handle work a blockchain is poorly suited to do directly: oracles connect contracts to external data, indexing services organise on-chain records, and storage protocols handle larger files. A wallet and a conventional website form the interface people see. Because these components are interdependent, an application may rely on several networks and companies even when its primary contracts are decentralised.
Web3 crypto coins and tokens are digital assets associated with blockchain networks or decentralised services. People often use the two terms interchangeably, but technically a coin is native to its own blockchain, while a token is typically issued using an existing blockchain’s standards.
Ether (ETH), for example, is the native asset of Ethereum and is used to pay network fees. Chainlink’s LINK is a token associated with decentralised oracle services that help smart contracts use off-chain data. Filecoin’s FIL supports an open marketplace for data storage.
The relationship between a Web3 project and its token matters: a useful application does not automatically make its token a good investment. Demand, supply, incentives and competition all affect token economics. Our comparison of Web3 crypto coins and their use cases shows how tokens support different types of blockchain infrastructure.
| Category | What the tokens may do | Examples |
| Smart-contract platform coins | Pay network fees and support application activity | ETH, SOL |
| Oracle tokens | Support services that connect blockchains with external information | LINK |
| Decentralised storage tokens | Reward storage providers or pay for data services | FIL, AR |
| Blockchain data tokens | Support indexing and querying on-chain information | GRT |
| Interoperability tokens | Support governance, security or cross-chain ecosystems | DOT |
| DeFi and governance tokens | Provide voting rights or incentives in a protocol | Varies by application |
Categories can overlap, and token designs change. The examples are illustrative, not a ranking or a recommendation to buy.
These terms are related but not interchangeable. A native coin is the built-in asset of a blockchain, such as ETH on Ethereum or SOL on Solana. A token is created through a contract or token framework on a blockchain. Some tokens are designed for payments, access, staking or governance; others mainly represent claims, incentives or community participation.
An NFT is a non-fungible token associated with a distinct identifier; it may represent an item, membership or record, but does not automatically convey copyright or legal ownership of a physical asset. A stablecoin aims to track a reference asset, commonly a fiat currency, but the stability depends on its reserves, issuer, redemption rules or design. The label “Web3 coin” is therefore an informal category, not a technical or regulatory classification.
Some networks need native assets to pay validators, purchase computing resources or discourage malicious behaviour through staking and penalties. In other systems, a token is used for governance votes or rewards for storage, indexing and other services. A token is not inherently necessary for every online application, and adding one can introduce speculation, complex incentives and compliance obligations.
To assess a token, ask a practical question: if many more people use the product, what specifically happens to demand for the token? Fees may be paid in it, participants may need to lock it, or the token may only be used for voting. Those designs have different economics. Growing user numbers or a successful company do not guarantee that the corresponding token price will rise.
DeFi applications can allow users to exchange or lend digital assets through blockchain protocols. These services can remove certain intermediaries, but expose participants to smart-contract bugs, liquidity risk and scams.
Tokens can represent game items, membership passes or access rights. Ownership of the token does not necessarily transfer intellectual property rights, guarantee resale value or keep an application online.
Networks such as Filecoin and Arweave explore ways to distribute or preserve digital data using economic incentives rather than relying solely on one cloud operator.
Tools such as The Graph help applications retrieve blockchain information. Wallet-based sign-in can also let someone use a cryptographic identity across supported applications, although privacy depends on how each service is designed.
The clearest differences concern who manages the account, where records are kept and who can authorise a transaction. On a Web2 platform, recovery usually goes through a company account. On a self-custody Web3 wallet, control comes from the private key or recovery phrase.
This creates new possibilities, but also responsibility. If someone loses their recovery phrase or approves a malicious transaction, recovery may be difficult or impossible. In addition, many Web3 apps still rely on centralised websites, hosting, exchanges and teams.
Read in detail about the web3 and web2 Differences
Decentralisation is a spectrum. A blockchain might have many validators but a wallet provider could still operate the only convenient interface. An application might use audited open-source contracts while a small team controls upgrade permissions. Even a token-based DAO can have highly concentrated voting power if a few holders possess most of the supply.
Before describing a project as decentralised, examine who can pause contracts, change fee rules, control treasury funds, host the front end and block users from an interface. Also look at how independent validators are and whether people can switch to another application without losing their assets or data. This produces a more accurate picture than relying on a project’s marketing claims.
A crypto wallet can function as both an asset-management tool and an identity credential. Instead of creating a different account for every application, users can sometimes authenticate by signing a message with an address. The application may not require a traditional email address, but that does not automatically provide anonymity. A public address can be linked to transactions, and other websites may connect it to a person.
Two common wallet models are custodial and self-custody. With custodial services, a provider manages the keys or asset records. With self-custody, the user must secure their recovery phrase or key material. A misplaced phrase, compromised device or misleading transaction approval can lead to permanent loss. Privacy and control improve only when the surrounding design and user practices support them.
Myth: Web3 means every platform is fully decentralised. Reality: many projects rely on conventional cloud services, teams and administrative keys. Myth: all blockchain information is private. Reality: public ledgers often make transfers visible, even when an address is pseudonymous. Myth: owning a governance token makes you a legal shareholder. Reality: token rights are defined by the protocol and legal documents, if any.
Myth: every useful Web3 project has a valuable investment token. Reality: token price can be affected by supply schedules, speculation and competition regardless of product adoption. Myth: blockchain activity cannot be reversed in any circumstances. Reality: individual transfers are generally difficult to reverse, but protocols can change, assets can be frozen under some designs, and exchanges may control their own ledgers.
Potential benefits include verifiable transactions, transferable digital assets, open participation in some networks and the ability to build services on shared protocols.
Important limitations include volatile tokens, transaction fees, network congestion, wallet complexity, fraud, smart-contract vulnerabilities and uncertain governance outcomes. Public blockchains are often transparent rather than automatically private. No system is completely secure or immune to censorship.
Begin with the official documentation and verify the domain name from more than one trustworthy source. Look for named developers, transparent contract addresses, independent security reviews and a description of who can upgrade critical code. Check whether the project publishes clear information about network fees, outages, access restrictions and what happens if the service is discontinued.
For a token-based project, review the circulating and maximum supply, scheduled unlocks and how tokens are actually used. Explore blockchain data rather than relying only on social posts; understand that unusually high on-chain activity can sometimes come from bots or incentives. If an application asks for unlimited spending approvals, wallet seed phrases or transfers to claim a prize, avoid it. No checklist eliminates risk, but it can catch obvious problems.
DApp: an application that uses decentralised infrastructure for some of its functions. Smart contract: blockchain-executed code that can hold assets and apply predefined rules. Gas fee: a charge for processing a blockchain transaction. Bridge: a tool used to transfer or represent assets between networks, often introducing additional risks. Oracle: a service supplying external data to smart contracts.
DAO: a group that coordinates decisions, sometimes through on-chain voting. Seed or recovery phrase: words that can restore access to a self-custody wallet and must never be shared. Block explorer: a website for examining public blockchain transactions. Tokenomics: the rules governing a token’s issuance, distribution, utility and incentives. These definitions are a starting point; implementation varies by network.
Start by reading project documentation, examining a blockchain explorer and learning how wallets and transaction approvals work. Some educational applications offer test networks or public dashboards that do not require a financial commitment.
Understanding how Web3 works is different from deciding whether to invest in a token. For readers considering a purchase, our step-by-step guide to investing in Web3 coins in India explains INR buying, custody choices, fees and important risks.
Also Read: How to invest in Web3 Crypto Coins
To see the live market data of supported tokens, explore Web3 crypto coins on Mudrex. Prices and availability can change, so research each asset before placing an order.
No single person invented every idea behind Web3. Ethereum co-founder Gavin Wood helped popularise the term “Web3” in the blockchain context in 2014. The underlying technologies, including cryptography, peer-to-peer networks and blockchains, emerged from many contributors over decades.
Yes. Examples include blockchain transfers, decentralised exchanges, on-chain identity systems, token-based games, data indexing and distributed storage networks. Adoption varies, and many products still rely on centralised providers for interfaces, customer service or infrastructure.
The major risks include volatile token prices, malicious applications, lost private keys, protocol exploits, high fees and unclear legal rights. Some risks come from software design and others from user behaviour. A blockchain does not make every application on top of it trustworthy.
Web3 may influence how online payments, ownership and identity work, but its long-term adoption is uncertain. It is more realistic to expect combinations of conventional internet services and blockchain systems than to assume an immediate or complete replacement of Web2.
No. Web3 describes a broader approach to internet applications, while cryptocurrency refers to digital assets. Cryptocurrencies can provide payments and incentives within Web3, but the two terms are not interchangeable.
A Web3 coin or token is a digital asset used by a blockchain network or Web3 service. It may pay fees, reward network participants, provide access to a service or support governance.
Bitcoin is a cryptocurrency and blockchain network, but it is not usually grouped with application-focused Web3 infrastructure tokens. Classifications vary by website and context.
In crypto discussions, the names are generally used interchangeably. Historically, “Web 3.0” has also been used for the semantic web, so context matters.
Not always. You can read blockchain data or explore some apps without buying a token. On-chain transactions generally require network fees or an application that pays those fees on your behalf.
Examples include ETH and SOL for smart-contract platforms, LINK for oracles, FIL and AR for storage, GRT for blockchain data and DOT for interoperability and network governance.
No. Many Web3 products combine blockchain systems with centralised front ends or service providers. Public transaction histories can also be visible, so decentralisation and privacy must be assessed separately.
You cannot buy “Web3” as one asset. You can research and purchase particular crypto assets or gain exposure to companies working on related technologies. You can Signup on Mudrex and start investing in Web3 Crypto coins.
Disclaimer: This article is for education only and does not constitute investment advice. Cryptocurrency prices can be highly volatile and losses can be substantial.