Wall Street’s average Amazon stock price prediction sits near $328, about 30% above where the stock trades today around $254. That is the widest upside analysts see across the big tech giants right now. The reason is a split screen: the cloud business is growing at its fastest pace in over four years, while a record spending bill has pushed cash flow negative.
This Amazon stock price prediction walks through the analyst targets, the numbers that matter, the spending debate at the heart of it, and a clear verdict for 2026 through 2030.
The Snapshot
Metric
Value
Trading near
$254
Analyst average target
$321 to $331
Upside to target
About 26% to 30%
Rating
Strong Buy (almost no Sells)
52-week range
$196 to $287
Market cap
About $2.74 trillion
Next earnings
Oct 29, 2026
Key Details
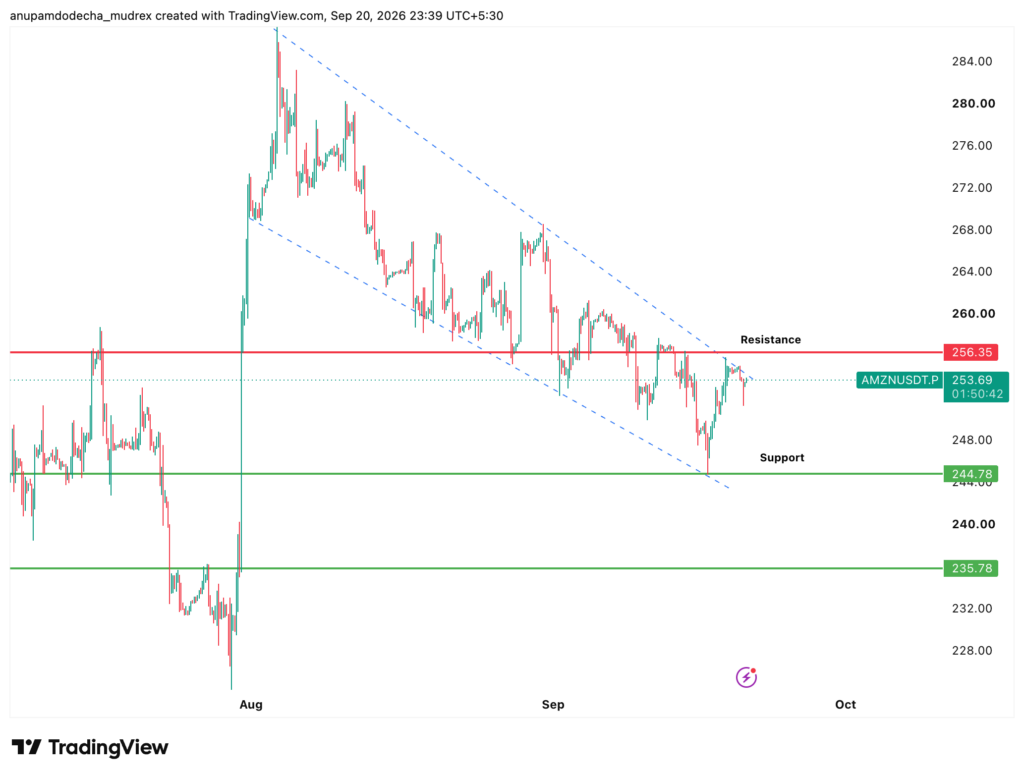
Amazon Stock Price Chart
Amazon in One Look: Three Engines, One Big Bill
Amazon is really three businesses under one roof, and understanding that split is the key to any Amazon stock price prediction.
Retail and logistics: North America and International stores, Prime, and fulfillment. Huge revenue, thin margins, and the reason Amazon reaches nearly every household.
Advertising: the quiet high-margin engine inside retail, growing 26% last quarter.
AWS (cloud and AI): the profit powerhouse. It grew 37% last quarter, its fastest in 18 quarters, at a roughly 39% profit margin.
The catch is the bill. Amazon is spending a record $220 billion in 2026, mostly on AI and cloud capacity. That spending is so large it has turned trailing free cash flow negative. So the whole debate comes down to one question: is that spending building the next decade of growth, or just burning cash?
Ignore the noisy headline profit. Last quarter’s reported earnings of $5.75 per share were inflated by a one-time $53.4 billion paper gain on Amazon’s Anthropic stake. Strip that out and these are the clean figures that count.
Segment
Revenue
Growth
Profit
North America retail
$116.2 billion
+16%
$9.1 billion
International retail
$42.2 billion
+15%
$1.7 billion
AWS (cloud)
$42.2 billion
+37%
$16.6 billion
Advertising
$19.8 billion
+26%
high margin
Total sales
$200.6 billion
+20%
first $200B quarter
Operating income jumped 43% to $27.5 billion. The story in one line: the profitable parts are accelerating, but the capex bill is the cloud hanging over it all.
For 2026, the Amazon stock price prediction leans clearly bullish, with an average target around $328 versus $254 today. But the stock has to clear a near-term overhang first.
Scenario
2026 target
What drives it
Bull
$360 to $405
AWS stays in the high 30s, capex peak comes into view
Base
$321 to $331
AWS holds mid-30s, ads compound, retail margins hold
Bear
$230 to $247
AWS slows to the 20s, another capex raise, weak Q4 guide
The near-term checkpoint is the October 29 Q3 report. Three things decide the reaction: the AWS growth rate, the Q4 guide, and whether $220 billion in capex is the peak or the floor. Clear those and the path opens toward $262 and beyond. Disappoint and the mid-$230s come back into view.
The longer-term Amazon stock price prediction rests almost entirely on the payoff from today’s spending.
2027: This is the “prove it” year. Amazon’s CEO argues that data-center servers pay back in about three years and that AI returns are tracking a bit ahead of the early cloud days. If that holds, free cash flow should turn positive again as revenue outgrows the spending. One wrinkle: reported earnings estimates for 2027 actually dip in some models because the one-time Anthropic gain will not repeat, so watch operating income and cash flow, not headline EPS.
2030: If AWS keeps compounding and AI workloads scale as expected, several long-term forecasts put Amazon well above $400. The bet is that Amazon becomes one of the core platforms companies run their AI on, using its own Trainium chips to take share from pricier options. If cloud growth fades or power and capacity slip, that re-rating slides further out.
Long-dated targets are estimates, not promises. The further out you look, the wider the range.
The Capex Debate: Bull vs Bear in One Table
Every Amazon stock price prediction ultimately argues about the spending. Here are both sides.
Bulls say
Bears say
$220B builds the AI backbone of the next decade
Spending could rise again and delay cash flow
AWS at +37% with a $496B backlog proves demand
AWS could slow if power or capacity slips
Ads compounding 26% at high margin
A consumer slowdown could hit retail
Free cash flow recovers as spending annualizes
Free cash flow could stay negative into 2027
Cheap at ~20x earnings for this growth
That paper gain can reverse and swing profit down
Bull vs Bear Case
If you side with the bulls, $254 looks like a discount created by capex fear. If you side with the bears, you wait for proof the spending pays off.
A few things outside the core numbers could swing the Amazon stock price prediction.
Power and chips: Electricity is now as important as GPUs. Amazon signed an $8 billion backup-generator deal in September 2026 to secure data-center power, and its custom Trainium chips aim to cut reliance on expensive third-party silicon.
AI strategy reset: Amazon paused several in-house models and refocused on being the infrastructure, chips, and distribution layer for AI rather than only a frontier-lab rival. Anthropic runs on AWS and is both a big customer and a source of that swinging paper gain.
Regulation and labor: Amazon faces ad-auction cases from the FTC and states, a driver-labor suit, and ongoing retail-competition cases. These are overhangs, not immediate earnings events.
Amazon Leo (satellite internet): Around 400 satellites are up so far, with limited broadband targeted before end-2026. It is still a multi-year cash user, but the enterprise angle of linking it to AWS gives it a purpose beyond copying Starlink.
Key Price Levels to Watch
For timing an entry, these are the levels that matter around $254.
Level
Meaning
$262 to $266
First real breakout zone to reclaim
$255 to $256
The 20-day and 50-day averages, immediate resistance
$254
Roughly where it trades now
$246 to $250
Key support, near the 200-day average
$235 to $240, then $196
Deeper support and the 52-week low
Key levels
Amazon sits above its 200-day average but below its 20-day and 50-day, a classic mid-range digest after a failed high. RSI is neutral near 48. A daily close back above $256 would suggest the slide is over. A break under $247 then $240 opens a deeper test toward the mid-$230s.
So, Is Amazon Stock a Buy?
Here is the verdict. Amazon offers the widest analyst upside among the big tech names, backed by a cloud business firing on all cylinders and a high-margin ads engine most people forget about. The catch is the spending: until free cash flow turns positive again, expect the stock to stay choppy and headline-driven.
For long-term investors who can look past the capex fear to the 2027 cash flow recovery, the Amazon stock price prediction is compelling. For those who need clean cash flow and low volatility today, waiting for proof at the October report is reasonable.
A qualified financial professional should own your final call. This is general information, not personalized advice.
What is the Amazon stock price prediction for 2026? The average analyst target is around $321 to $331, roughly 26% to 30% above the current price near $254. The full range runs from about $230 on the low end to $405 on the high end, reflecting the split over Amazon’s heavy spending.
What is the latest analyst price target for AMZN? The consensus target clusters around $328 with a Strong Buy rating from most of the roughly 60 analysts covering it. There are almost no Sell ratings, though targets range widely from about $230 to $405, with recent bullish calls like Barclays at $365 and Evercore at $355.
Is Amazon stock a good investment? Amazon suits long-term investors who believe its cloud and AI spending will pay off and can tolerate near-term volatility and negative free cash flow. It is a growth-oriented holding with the widest analyst upside among big tech, not a low-volatility income stock.
What could make AMZN stock rise? AWS staying in the mid-30s or better, advertising compounding in the mid-20s, North America retail margins holding near 8%, capex growth slowing relative to AWS growth, Trainium chips taking share, and free cash flow turning positive again in 2027.
What are the biggest risks for Amazon stock? Another capex increase, free cash flow staying negative into 2027, AWS slowing if power or capacity slips, a consumer slowdown hitting retail, the Anthropic paper gain reversing, legal outcomes on ads or labor, and the Leo satellite project staying a cash drain.
Is AMZN stock overvalued or undervalued? At about 20x trailing earnings it looks cheap for this growth, but that number is distorted by one-time gains and ignores negative free cash flow. Most analysts still see clear undervaluation, which is why the average target sits about 30% higher than the current price.
Can Amazon stock reach a new all-time high? It would need to clear its $287 high from August 2026. With AWS accelerating and analyst targets averaging around $328, many analysts expect it, but it likely requires proof at the October earnings that the heavy spending is turning into cash.
How can investors in India invest in AMZN shares? Indian investors can buy Amazon shares on Mudrex, which supports US stock investing with fractional shares so you can start small without paying for a full share. Factor in currency conversion and fees, and keep AMZN as part of a diversified portfolio.
Anupam has over 3 years of experience in the crypto industry, having worked with top indian crypto exchanges. He writes about Bitcoin, altcoins, AI, and emerging tech, helping readers understand what’s driving markets and where the digital asset ecosystem is headed.