Quick answer: PayPal (NASDAQ: PYPL) is a classic value and turnaround story. As of September 22, 2026, PYPL trades near $53 at just 10x earnings, cheap because growth is slow and its core checkout business has been stuck for years. The average analyst target sits around $56 to $58, only modest upside, with a wide range from about $32 to $80. The whole debate: was the recent failed $60.50 buyout bid a floor, or was $53 a spike?
Key Takeaways
Timeframe
Likely Range
Move from ~$53
Today (Sep 2026)
$53
—
12-month target
$56–$58
+6% to +8%
End of 2026
$48–$62
−9% to +17%
2027
$55–$70
+4% to +32%
2030 (bull case)
$70–$100
+32% to +89%
PayPal Stock Price targets
If you own PayPal stock, you probably have one question: after a failed takeover and a beaten-down price, is this a bargain or a value trap? This PayPal stock price prediction walks you through the numbers, the bull case, the bear case, and the risks so you can make up your own mind.
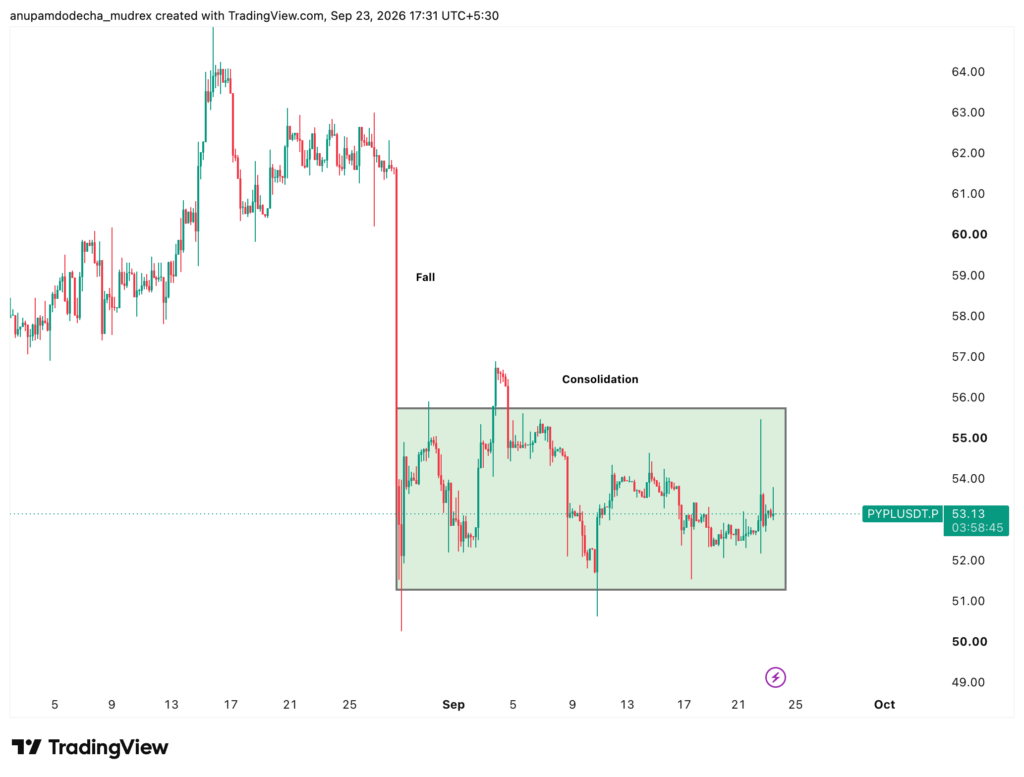
Paypal Stock Price Chart
Where PayPal Stock Stands Right Now
Before any PayPal stock price prediction can seem meaningful, let’s look at where things stand today.
PayPal (PYPL) closed at $52.89 on September 22, 2026, up 0.51% on the day. The company is now worth about $45 billion. The stock is down roughly 30% over the past year and sits far below its 52-week high of $79.22, though it has rallied hard off its $38.46 low.
Here’s the quick snapshot:
Metric
Value
Price (Sep 22, 2026)
$52.89
Market cap
~$45 billion
52-week range
$38.46 – $79.22
P/E ratio (trailing)
10x
Forward P/E
9.5x
Dividend yield
1.1% ($0.56/yr)
Next earnings
Oct 27, 2026
Paypal Stock Key Figures
The big talking point for any PYPL stock prediction is that failed buyout. In July 2026, Stripe and Advent bid $60.50 for PayPal, sending the stock as high as $62.30. Talks collapsed in late August over price, and the stock fell back to the low $50s. PayPal now trades below the dead bid, and that’s the entire debate: either the offer marked a floor and management can grow into $60+, or $53 was a spike and PayPal’s fair value as an independent company is closer to $38 to $45.
PayPal’s Latest Earnings: The Numbers Behind the Forecast
Every PayPal stock forecast starts with the most recent earnings. On July 28, 2026, PayPal reported Q2 2026 results. It beat expectations, but the quality was mixed: decent volume, but margins and EPS still shrinking.
Metric
Result
Change
Revenue
$8.68 billion
+5%
Total Payment Volume (TPV)
$486.4 billion
+10%
Active accounts
439 million
Flat YoY
Non-GAAP EPS
$1.38
−1% (beat estimates)
Non-GAAP operating margin
17.4%
Down 248 bps
Adjusted free cash flow
$1.8 billion
Strong
The story here is about a cash machine with a stalling core. Revenue and payment volume grew fine, but earnings per share still fell year over year, and operating margins compressed. The heart of the problem is branded checkout, the classic PayPal button, whose TPV grew just 2%. That’s the second straight quarter of “stabilized” low-single-digit growth after years of stagnation.
The brighter spots are the other two engines. Venmo TPV grew 14%, its seventh straight double-digit quarter, and Braintree (PayPal’s merchant processor) grew in the mid-teens for a ninth consecutive profitable quarter.
Management’s whole pitch is independence: stabilize checkout, turn Venmo into a real money app, grow Braintree, cut $1.5 billion of costs, and keep buying back stock.
Here’s how the three engines compare on growth:
PayPal Stock Price Prediction 2026, 2027 & 2030
The gap is stark. Venmo and Braintree are growing fast, while branded checkout, still the profit engine, is barely moving. That split sits at the heart of every PayPal stock price prediction.
PayPal Stock Price Prediction 2026
So where could PYPL finish the year? Here’s a simple PayPal stock price prediction 2026, broken into three scenarios.
Scenario
Target Range
What It Assumes
Bull case
$57–$62
Checkout stabilizes, buybacks bite
Base case
$52–$57
Range-bound, mixed signals
Bear case
$44–$50
Checkout weakens, no second bidder
PayPal Stock Price Targets
Base case ($52–$57)
The stock stays range-bound between its support shelf and its 50-day average as investors wait for proof the turnaround is working. Reasons: PYPL trades below its 20- and 50-day moving averages (around $55 to $57) but just above its 200-day (around $50.4). RSI near 41 is soft but not washed out. With a crowded Hold rating and the failed-deal hangover still clearing, a drift in the low-to-mid $50s fits the current setup unless the October earnings surprise in either direction.
Bull case ($57–$62)
This matches the recovery rungs on the chart and the low end of the failed bid. Reaching $62 would need real turnaround proof. Reasons: PayPal is buying back around $6 billion of stock a year, which has cut the share count by 10% and mechanically lifts EPS. At 10x earnings, that buyback is the core bull argument. Add another quarter of checkout growth above 2%, mid-teens Venmo and Braintree, and accelerating transaction-margin dollars, and the stock could reclaim $57 and push toward the old bid at $62. A fresh takeover offer would also help.
Bear case ($44–$50)
A slide toward $44 to $50 if the turnaround stalls. Reasons: If branded checkout slips back to flat or negative, if Venmo stays a low-take-rate payment toy, or if operating expenses stay hot while EPS keeps falling, the “cheap” multiple starts to look cheap for a reason. Losing technical support at $52.15 opens the door to $50.80, then $48. In a weak-consumer scenario, the pre-bid base near $38 to $45 comes back into play. Competition from Apple Pay, Google Pay, Stripe, and Affirm is the constant threat.
For 2026, the odds are genuinely balanced, which is why Wall Street sits on a crowded Hold. October’s earnings are the next real catalyst.
PYPL Stock Prediction 2027
Look one more year out and the PayPal stock price prediction 2027 comes down to a single question: does the core franchise stop shrinking?
Analysts see FY2027 EPS clustering around $5.80, up from roughly $5.38 in 2026. That’s mid-single-digit growth at a single-digit multiple, which is only attractive if PayPal proves the checkout business has truly stabilized. Applying a modest re-rating to that earnings base gets you to a $55 to $70 range for 2027.
The bullish anchor is the buyback plus the Venmo and Braintree story. If Venmo finally monetizes (through its debit card, “Pay with Venmo,” a possible bank charter, and super-app features), and Braintree keeps compounding, PayPal’s growth mix improves and the market may award a higher multiple. If not, the stock stays stuck as a cash-generative but shrinking franchise.
PayPal Stock Price Prediction 2030
Long-term forecasts are less about next quarter and more about whether PayPal remains relevant in a payments world crowded with Apple, Google, and Stripe.
The most bullish view sees PYPL reaching $70 to $100+ over the coming years if the turnaround fully works. From today’s price near $53, the high end would be nearly 90% upside. That scenario needs branded checkout to reaccelerate, Venmo to become a genuine money app, and years of buybacks to shrink the share count meaningfully.
The logic is straightforward. PayPal generates over $6 billion in free cash flow a year. If it stops losing checkout share and turns Venmo into a real revenue engine, a higher valuation multiple on a smaller share count could lift the stock substantially. Price would follow.
Of course, multi-year forecasts carry real uncertainty. If checkout keeps leaking share to Apple Pay and Stripe, PayPal risks becoming a slowly declining cash cow, and the low multiple would be fully justified. That’s the tension in every long-term PayPal stock forecast: cheap and recovering, or cheap and fading.
Latest Analyst Price Targets for PYPL
Wall Street’s consensus on PayPal is a crowded Hold, and that says a lot. After the takeover bid died, almost nobody is pounding the table.
The average 12-month target sits around $56 to $58, only 6% to 8% above today’s price. Here’s how the ratings and targets break down:
Detail
Value
Consensus rating
Hold (9 Buys, 34 Holds, ~4 Sells)
Average target
$56–$58
High target
$70–$80 (RBC, KBW, Argus at $70)
Low target
$32–$36 (Redburn Sell at $36)
Implied upside (avg)
+6% to +8%
The bullish view rests on the cheap valuation, the huge buyback, and the Venmo and Braintree growth engines. The bearish view focuses on the stagnant checkout business, thin margins, and fierce competition. The wide target spread, from $32 to $80, shows how divided opinion is.
Bull Case vs Bear Case: The Honest View
Every good PayPal stock forecast weighs both sides. Here’s the fair version.
The Bull Case (Why PYPL Could Climb)
Cheap valuation. Just 10x earnings, with a 9.5x forward P/E.
Massive buyback. Around $6 billion a year, cutting the share count ~10%.
Venmo is growing. 14% TPV growth and rising card adoption.
Braintree compounds. Nine straight profitable-growth quarters.
Takeover interest. The $60.50 bid showed someone saw value here.
The Bear Case (Why PYPL Could Fall)
Checkout is stagnant. The core profit engine grew just 2%.
EPS is still shrinking. Non-GAAP EPS fell year over year despite the beat.
Margins compressing. Operating margin down 248 bps.
Fierce competition. Apple Pay, Google Pay, Stripe, and Affirm all circling.
No second bidder yet. The stock is an “orphan” again below the dead bid.
Is PayPal Stock Overvalued or Undervalued?
This is the question behind every PayPal stock price prediction, so let’s tackle it head-on.
On paper, PayPal looks cheap. At 10x trailing earnings and 9.5x forward, it trades well below the broader market and most fintech peers, while throwing off more than $6 billion in free cash flow a year. For a value investor, that’s the appeal.
But cheap can stay cheap. The low multiple reflects real worries: mid-single-digit revenue growth, a stagnant core, and shrinking EPS. So the honest answer is: undervalued if branded checkout stabilizes and Venmo monetizes, a value trap if the franchise keeps leaking shares. The multiple is low for a reason, and the reason has to go away for the stock to re-rate.
A qualified financial advisor should help make the final call for your situation.
How to Buy PayPal Stock in India
Mudrex has expanded Spot trading to include tokenized US Stocks, and PayPal is among the names available, alongside Nvidia, Tesla, and others.
Open the Mudrex app and complete your KYC (same process as setting up for crypto trading).
Fund your account in INR.
Search for PayPal on Mudrex Spot.
Place a buy order; you can start with amounts far smaller than a full PYPL share would cost through a US broker, since tokenized spot trading typically allows fractional exposure.
Disclaimer: This article is for educational purposes only and is not investment advice. Prices are volatile and can fall as well as rise. Do your own research and consult a qualified financial advisor before investing. Invest only what you can afford to lose.
FAQs
What is the PayPal stock price prediction for 2026?
Most analysts expect PayPal stock to finish 2026 between $52 and $57 in the base case. The bull case reaches $57 to $62 if branded checkout stabilizes and buybacks support the price, while the bear case sees $44 to $50 if the turnaround stalls. The average 12-month target is around $56 to $58.
What is the latest analyst price target for PYPL?
The average 12-month analyst target is around $56 to $58, roughly 6% to 8% above the current price near $53, with a consensus rating of Hold. Targets range widely, from about $32 on the low end to $70 to $80 on the high end.
Is PayPal stock a good investment for Indian traders?
It depends on your view of the turnaround. Bulls point to the cheap 10x valuation, a large buyback, and growth at Venmo and Braintree. Bears point to stagnant checkout and shrinking EPS. It’s a value-and-turnaround bet, not a growth story. It’s not investment advice, so do your own research first.
What could make PYPL stock rise?
Continued stabilization in branded checkout, real Venmo monetization, mid-teens Braintree growth, cost savings flowing through, the $6 billion buyback shrinking the share count, or a fresh takeover bid could all push PayPal stock higher.
What are the biggest risks for PayPal stock?
The main risks are a stagnant or declining checkout business, Venmo failing to monetize, margins compressing while EPS falls, fierce competition from Apple Pay, Google Pay, Stripe, and Affirm, and no second buyer emerging after the failed bid.
Can PayPal stock reach a new all-time high?
It’s a long way off. PayPal’s stock is far below its past highs, and reaching a new all-time high would require a full turnaround: reaccelerating checkout, a monetized Venmo, and years of buybacks. In the nearer term, analysts see the low-to-mid $50s, with bulls targeting $70.
Anupam has over 3 years of experience in the crypto industry, having worked with top indian crypto exchanges. He writes about Bitcoin, altcoins, AI, and emerging tech, helping readers understand what’s driving markets and where the digital asset ecosystem is headed.