Quick answer: Qualcomm (NASDAQ: QCOM) is a cash-rich chipmaker trying to prove it’s more than a phone company. The stock trades near $184, and most analysts see only modest upside over the next year. The real debate is bigger than that: its phone business is shrinking as Apple pulls away, but its car-chip business is booming and a new AI data-center bet could change the whole story.
Timeframe
Where analysts/scenarios point
Today
~$184
Next 12 months
~$194–$205 (modest upside)
2027
Higher if car and AI chips deliver
2030
Much higher in the bull case, if the turnaround works
Key Takeaways
If you own Qualcomm stock, you probably have one question: with phones fading but cars and AI rising, is this cheap stock a bargain or a trap? Here’s the full picture.
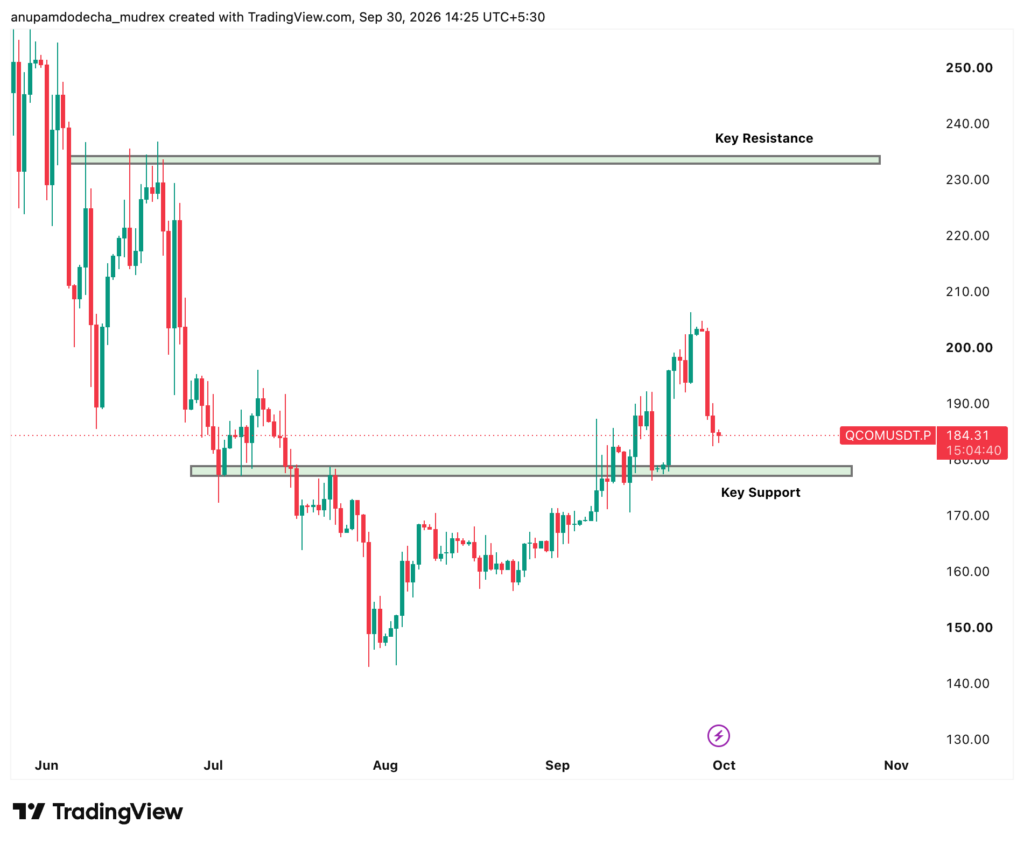
QCOM Price Chart
Where Qualcomm Stock Stands Right Now
Qualcomm makes the chips inside smartphones and earns royalties on the technology behind them. For years, phones were their whole story. Now the company is trying to stand on three legs instead of one: phones, car chips, and a brand-new AI data-center business.
The stock has had a rough stretch, down about a third from its high, though well up from its lowest point. Investors are cautious because the phone business is slipping, and they’re waiting to see if the newer businesses can pick up the slack.
Metric
Value
Price
~$184
Market cap
~$197 billion
Dividend yield
2.0%
Valuation
Cheap vs. other chipmakers
Next earnings
Early November 2026
Key Info
The one idea to hold onto: the market is still pricing Qualcomm like a phone company and giving it little credit for cars or AI. That’s the gap the whole debate is about.
The Latest Earnings: Strong Cars, Weak Phones
Qualcomm’s most recent results told a split story, weak in phones, strong in cars.
The phone chip business, still about half the company, dropped sharply as Apple keeps switching to its own chips and costs rose. But the car business grew more than 60% and hit a record, its 23rd straight strong quarter. The smaller “smart devices” business (things like industrial gadgets and networking) grew too.
Quietly funding all of this is Qualcomm’s licensing business, where it collects royalties at very high profit margins. That steady cash is what pays for the dividend, the share buybacks, and the investment into new areas.
The whole story in one chart: phones going down, cars racing up. Qualcomm’s future depends on cars (and later, AI chips) growing faster than phones shrinking.
Qualcomm Stock Price Prediction 2026
Here’s where the stock could realistically go by year-end, in simple terms.
Scenario
Rough Direction
What needs to happen
Bull case
Back toward its recent highs
Phones steady, cars stay hot
Base case
Roughly where it is now
Mixed signals, wait-and-see
Bear case
Lower
Apple hits harder, phones weaken
Qualcomm Price Cases
Qualcomm Stock Price Targets
Base case
The most likely path for now is sideways. The stock is holding above its longer-term averages but hasn’t broken out. Without a clear catalyst, it may just drift in a range until the next earnings report gives investors a reason to move.
Bull case
If the next results show phone sales steadying, the car business staying strong, and the new AI data-center unit finally bringing in real money, sentiment could turn and the stock could climb back toward its recent highs.
Bear case
If Apple pulls away faster, rival chipmaker MediaTek keeps winning, or the AI business disappoints, the stock could slide back toward its lows. Phones are still the swing factor.
For 2026, it’s genuinely balanced, which is why most analysts are sitting on the fence. The early-November earnings report is the next big test.
Qualcomm Stock Price Prediction 2027
Looking a year further out, it comes down to one question: can the newer businesses grow fast enough to make up for shrinking phones?
Analysts expect profits to recover in 2027 after a soft 2026. The key driver is Qualcomm’s plan for its car and AI-chip businesses to become a much bigger share of the company. The biggest wildcard is the new data-center business: it’s aiming to go from almost nothing today to a meaningful business, with its first custom AI chips starting to ship soon. If those early wins prove real, the stock could re-rate higher. If the AI push stays just talk, the stock likely stays stuck.
Qualcomm Stock Price Prediction 2030
Long term, the question is whether Qualcomm’s three-legged plan actually holds together.
Management has laid out an ambitious goal: by the end of the decade, most of its chip revenue should come from cars and AI rather than phones, with profits far higher than today. If it gets even close, the stock could be worth substantially more than it is now, potentially well above its old highs.
The logic is fairly simple: if Qualcomm can keep growing its automotive business, win more AI customers in the cloud, and continue generating licensing revenue, it has a chance to evolve from a phone-chip company into a much more diversified technology platform. If that growth comes through, the stock could benefit too.
But there’s no shortage of competition. Apple is moving away from Qualcomm, MediaTek continues to gain ground in smartphones, while Nvidia remains a major force in both automotive and AI chips. Qualcomm has to compete with all three, which makes the opportunity far from certain. That’s what makes the story interesting: there’s meaningful growth potential, but the company has to prove it can take market share in several highly competitive businesses at the same time.
Qualcomm (QCOM) Technical Analysis
For readers who follow charts, here’s the short version.
The stock is stuck in the middle of a range, recovering from a big drop but not breaking out. It’s trading above its longer-term trend lines, which is healthy, but momentum is neutral, so it’s a wait-and-see setup rather than a clear signal in either direction.
Zone
Level
Old high (big resistance)
~$260
Nearby ceiling
~$206
Current area
~$184
First support
~$182
Stronger support
~$170
Danger line
~$122 (52-week low)
Key Levels
In plain terms: as long as it holds around $182, the trend stays intact and a push toward $206 (then eventually $260) is possible. If it breaks below $170, the mood sours and the old lows come back into view. Expect bigger swings around earnings.
Technical analysis for education, not financial advice. Qualcomm is volatile, so size positions accordingly.
Latest Analyst Price Targets for QCOM
Wall Street is mostly on the fence, more “Hold” than “Buy.” The average target sits only modestly above today’s price, though opinions vary a lot.
Detail
Value
Overall rating
Hold / Moderate Buy
Average target
~$194–$205
Most optimistic
$220 (with one big outlier)
Most cautious
~$158–$170
Price Targets
The optimists like the cheap price, the booming car business, and the AI potential. The skeptics worry about shrinking phones and strong competition. The wide gap between them tells you how split the opinion is.
The new AI data-center bet could open a huge market.
$5.6B licensing revenue at a 72% EBT margin gives Qualcomm steady, high-margin cash flow.
$8.8B in FY2025 buybacks plus a new $20B authorization support shareholder returns.
Why Qualcomm could fall
The phone business is shrinking.
Apple is switching to its own chips.
Rival MediaTek is winning in phones.
Nvidia dominates the car and AI markets Qualcomm wants.
Profits are expected to dip before they recover.
Is Qualcomm Stock Overvalued or Undervalued?
On the surface, Qualcomm looks cheap, it trades well below most other chipmakers and pays a solid dividend. That’s the appeal for value investors.
But cheap can stay cheap. The low price reflects real worries about the fading phone business. So the honest answer is: it’s undervalued if cars and AI deliver, and a value trap if they don’t. The market wants proof before it pays more.
A qualified financial advisor should help make the final call for your situation.
How to Buy Qualcomm Stock in India
Mudrex has expanded Spot trading to include tokenized US Stocks, and Qualcomm is among the names available, alongside Nvidia, Tesla, and others. Broadly, the process looks like this:
Open the Mudrex app and complete your KYC (same as setting up for crypto trading).
Fund your account in INR.
Search for Qualcomm on Mudrex Spot.
Place a buy order; you can start small, since tokenized spot trading typically lets you buy a fraction of a share.
Qualcomm Stock Price Prediction 2026, 2027 & 2030
The Bottom Line
Qualcomm is a cheap, cash-generating chipmaker in the middle of a big makeover. Its car business is thriving and its AI bet is exciting, but its core phone business is shrinking and tough rivals stand in the way.
Most analysts see only modest gains over the next year, with bigger upside later if the turnaround works. If you believe cars and AI can outgrow the fading phone business, the low price is tempting. If not, it may stay cheap for a reason. The next big checkpoint is the early-November earnings report.
Disclaimer: This article is for educational purposes only and is not investment advice. Prices are volatile and can fall as well as rise. Do your own research and consult a qualified financial advisor before investing. Invest only what you can afford to lose.
FAQs
What is the Qualcomm stock price prediction for 2026?
Most analysts expect the stock to stay close to where it is for the rest of 2026, with modest upside if phones steady and cars stay strong, and downside risk if Apple’s exit and weak phone demand bite harder.
What is the latest analyst price target for QCOM?
The average 12-month target is modestly above today’s price, with a “Hold to Moderate Buy” rating. Views are split: the most optimistic see meaningful upside, while cautious analysts see little to none.
Is Qualcomm stock a good investment for Indian traders?
It depends on your view of the turnaround. Bulls like the cheap price, booming car business, and AI potential; bears point to shrinking phones and tough competition. It’s a value-and-transition bet, not a fast-growth story. Do your own research first.
What could make QCOM stock rise?
Phone sales steadying, the car business staying strong, the new AI data-center unit bringing in real revenue, and continued share buybacks could all lift the stock.
What are the biggest risks for Qualcomm stock?
Apple moving fully to its own chips, MediaTek winning more phone business, rising costs, and the AI push taking longer than hoped are the main risks.
Can Qualcomm stock reach a new all-time high?
It’s possible but would take time. The stock is well below its old high, and getting back there would likely need the car and AI businesses to grow enough to offset the phone decline.
Anupam has over 3 years of experience in the crypto industry, having worked with top indian crypto exchanges. He writes about Bitcoin, altcoins, AI, and emerging tech, helping readers understand what’s driving markets and where the digital asset ecosystem is headed.